What Are the Top 10 Questions a Chapter 7 Bankruptcy Trustee Will Ask You at Your Bankruptcy Hearing?

Published
One of the biggest concerns people have when filing Chapter 7 bankruptcy is the bankruptcy hearing. I hear it all the time from clients: “What are they going to ask me?” “Am I going to be questioned about everything I own?” “Is the trustee going to give me a hard time?”
The good news is that the Chapter 7 bankruptcy hearing is generally a relatively short and straightforward proceeding. Most of my clients are surprised at how uncomplicated it actually is.
After practicing bankruptcy law for more than 35 years and representing more than 25,000 individuals, I have attended thousands of these hearings. I have also appeared before every Chapter 7 trustee in the Eastern District of Michigan. I can tell you that while every trustee has their own style, there are certain questions that come up in virtually every Chapter 7 case.
Let’s take a look at the 10 questions you should be prepared to answer.
First, What Is the Bankruptcy Hearing?
The bankruptcy hearing is formally called the 341 Meeting of Creditors. It gets its name from Section 341 of the United States Bankruptcy Code.
After you file Chapter 7 bankruptcy, the United States Trustee’s Office appoints a Chapter 7 trustee to administer your bankruptcy case. One of the trustee’s responsibilities is to conduct your 341 hearing.
Despite its name, it is very unusual for creditors to actually attend. In most consumer Chapter 7 cases, the only person asking you questions will be the Chapter 7 trustee.
In the Eastern District of Michigan, these hearings are generally conducted by Zoom. You will receive instructions regarding the date, time, and how to participate.
For most Chapter 7 debtors, this will be the only hearing they will ever have to attend in their bankruptcy case. You generally will not have to appear in front of a bankruptcy judge.
The trustee will place you under oath and ask questions concerning your bankruptcy petition, financial affairs, assets, debts, and other information relevant to your case.
The purpose is not to embarrass you or make you uncomfortable. The trustee is trying to determine whether your bankruptcy paperwork is accurate and whether there are any assets or potential claims that could be administered for the benefit of creditors.
The Top 10 Questions a Chapter 7 Trustee Will Ask
1. Do You Own Any Real Estate?
This is one of the first and most important areas of inquiry for a Chapter 7 trustee.
The trustee wants to know whether you presently own or have any interest in real estate.
This includes:
- The home in which you presently live.
- A second home or vacation property.
- Vacant land.
- Rental properties.
- Commercial real estate.
- Property you own jointly with someone else.
- Any real estate in which your name appears on the deed.
You may be surprised to learn that even if you are not making the mortgage payments, or you do not consider yourself the actual owner, having your name on a deed can create an ownership interest that the trustee will want to investigate.
The trustee will generally want to know the approximate value of the property, the amount owed on any mortgages, and whether there is any equity.
Important: Do not assume that just because you own a house you cannot file Chapter 7 bankruptcy. Properly claiming available bankruptcy exemptions is often the key to protecting your home.
I represent homeowners in Chapter 7 bankruptcy cases every day. The important thing is to evaluate the equity and available exemptions before filing.
2. Do You Have Any Potential Lawsuits or Claims Against Anyone?
This is another extremely important question, and one that people sometimes overlook.
The trustee is interested in whether you have any potential legal claims that could result in a settlement or monetary award.
Examples include:
- Automobile accidents.
- Personal injury claims.
- Slip-and-fall accidents.
- Medical malpractice.
- Workplace injuries.
- Wrongful termination.
- Employment discrimination.
- Other claims against individuals or businesses.
Here is something important to understand: You do not have to have hired an attorney or filed a lawsuit for the trustee to be interested in your potential claim.
For example, suppose you were involved in an automobile accident before filing bankruptcy. You were injured, you have been receiving physical therapy, but you have not yet contacted a personal injury attorney.
You still have a potential claim, and that claim must be disclosed.
Even if you have not received a settlement offer, the trustee may want additional information about the circumstances of the accident and whether you anticipate pursuing a claim.
Failing to disclose a potential lawsuit can create serious problems. Always disclose it to your bankruptcy attorney before filing.
3. How Much Money Do You Have in Your Bank Accounts?
Trustees routinely ask about bank accounts and the balances in those accounts.
They may ask:
- What bank do you use?
- How many checking and savings accounts do you have?
- What was the balance on the date you filed bankruptcy?
- Do you have any other accounts?
- Do you have accounts at online banks or financial institutions?
The important date is generally the date your bankruptcy case was filed.
The trustee may also ask to see bank statements covering the period before filing.
One thing I emphasize to my clients is that you should be completely accurate when disclosing your bank accounts. Do not overlook an account simply because it has very little money in it or you rarely use it.
Also, do not assume that money in an account is automatically protected simply because it is needed to pay your monthly expenses. Exemptions must be properly evaluated and claimed.
4. Has Anyone Recently Died Who May Have Left You an Inheritance or Life Insurance Proceeds?
This is a question that catches some people by surprise.
The trustee wants to know whether anyone has recently passed away who may have left you money or property.
This includes:
- An inheritance from a parent.
- An inheritance from a grandparent.
- Life insurance proceeds.
- Money from an estate.
- An interest in a trust.
- Property transferred to you following someone’s death.
Under bankruptcy law, certain inheritances and life insurance proceeds acquired within 180 days after filing bankruptcy can become property of the bankruptcy estate.
This is why it is important to disclose not only money you have already received but also circumstances where you may be entitled to receive an inheritance.
For example, if your parent passes away shortly before you file bankruptcy, the trustee will want to know about it even if the estate has not yet been distributed.
5. Have You Filed Bankruptcy Before?
The trustee will generally ask whether you have filed bankruptcy previously.
If you have, you should be prepared to provide information about:
- When you filed.
- Whether it was Chapter 7 or Chapter 13.
- Whether you received a discharge.
- Whether the case was dismissed.
The trustee may have access to information about your prior bankruptcy filings, so there is no reason to be concerned about answering this question honestly.
Prior bankruptcy filings can affect your eligibility for a discharge in a subsequent case. For example, the general waiting period between Chapter 7 discharges is eight years, measured from the filing date of the first case to the filing date of the second case.
6. What Is Your Current Income, and Where Does It Come From?
The trustee will generally want to confirm your current employment and income information.
You may be asked:
- Where do you work?
- How long have you worked there?
- What is your gross monthly income?
- Are you paid weekly, biweekly, or monthly?
- Do you receive Social Security?
- Do you receive pension or retirement income?
- Do you have any other sources of income?
The trustee may compare your answers with the pay stubs, tax returns, and other financial documents provided in your bankruptcy case.
If your income has changed since filing, you should be prepared to explain why.
For example, perhaps you recently lost your job, retired, started receiving Social Security, or experienced a reduction in overtime.
These are ordinary circumstances, and the trustee simply wants accurate information.
7. Are You Married, and Does Your Spouse Work?
The trustee will generally ask whether you are married.
If you are married, you may also be asked about your spouse’s employment and income.
This is important because household income can be relevant to the Chapter 7 means test and the overall financial picture of your household.
A common misconception is that if only one spouse files bankruptcy, the other spouse’s financial circumstances are irrelevant. That is not necessarily true.
Even when only one spouse files, the trustee may have questions about household income, expenses, and financial arrangements.
You should also be prepared to explain whether your spouse maintains separate bank accounts or contributes toward household expenses.
8. What Caused You to Have to File Bankruptcy?
The trustee may ask why you are filing bankruptcy and what circumstances caused your financial difficulties.
For example:
- Did you lose your job?
- Did you experience a reduction in income?
- Did you go through a divorce?
- Did you experience a medical problem?
- Did your household expenses increase?
- Did you accumulate credit card debt?
- Did you fall behind on mortgage or automobile payments?
This is generally a straightforward question.
I always tell my clients that there is no requirement that you have experienced some extraordinary financial catastrophe before filing Chapter 7 bankruptcy.
You do not have to lose your job, get divorced, become seriously ill, or experience some other major life event.
Sometimes people simply find themselves in a financial situation where their debt has become unmanageable.
The trustee may be interested in understanding your financial circumstances, but you do not need to feel embarrassed about your reason for filing.
9. Have You Sold, Transferred, or Given Away Any Property Recently?
This is an important area of inquiry.
The trustee wants to know whether you have transferred property or given money or assets to anyone before filing bankruptcy.
Examples include:
- Giving a vehicle to a family member.
- Transferring your interest in a house to someone else.
- Selling property for less than its value.
- Giving money to children or relatives.
- Paying back a loan from a family member.
- Transferring money between accounts.
- Selling valuable personal property.
The trustee may ask about transactions occurring during the months or years before bankruptcy, depending on the type of transaction.
Certain transfers can be challenged as fraudulent transfers or preferential payments under the Bankruptcy Code.
That does not mean every payment or transfer is improper. People routinely sell vehicles, pay ordinary bills, and transfer money between accounts.
However, if you have made significant transfers or payments to family members, you should discuss them with your bankruptcy attorney before filing.
10. Have You Reviewed Your Bankruptcy Petition, and Is Everything in It True and Accurate?
This is one of the most basic questions asked at virtually every 341 hearing.
The trustee wants to confirm that you have reviewed your bankruptcy paperwork and that the information is accurate to the best of your knowledge.
You will generally be asked whether:
- You reviewed your bankruptcy petition and schedules.
- You signed the documents.
- The information is true and correct.
- You listed all your assets and liabilities.
- You disclosed all of your income and expenses.
- You understand that you have an ongoing obligation to disclose changes or newly discovered information.
This is why I spend considerable time reviewing bankruptcy paperwork with my clients before filing.
Your bankruptcy petition is a legal document filed under penalty of perjury. You should understand what is in it and make sure it accurately reflects your financial circumstances.
If something is incorrect, it should be brought to your attorney’s attention so that it can be corrected.
A Few Additional Questions You May Be Asked
Although the 10 questions above cover many of the most common subjects, trustees may ask additional questions depending on the circumstances of your case.
For example:
- Do you own any vehicles, boats, recreational vehicles, or other valuable property?
- Do you have any retirement accounts, pensions, or investment accounts?
- Do you own or have an interest in a business?
- Have you made any large purchases or cash withdrawals recently?
- Have you repaid any loans to family members?
- Are you expecting a tax refund?
- Do you have any safe deposit boxes?
- Are you holding money or property for someone else?
Every bankruptcy case is different. A trustee may have very few additional questions in a routine case, while a case involving real estate, business interests, personal injury claims, or unusual financial transactions may require considerably more discussion.
What Happens After the 341 Hearing?
For most Chapter 7 debtors, the 341 hearing is the only proceeding they will need to attend.
If the trustee is satisfied with your answers and does not need additional documentation, the hearing may be concluded in just a few minutes.
Sometimes the trustee will request additional information, such as bank statements, tax returns, mortgage information, vehicle titles, or other financial records.
That does not necessarily mean there is a problem with your case. It is simply part of the trustee’s responsibility to investigate the financial affairs of the debtor.
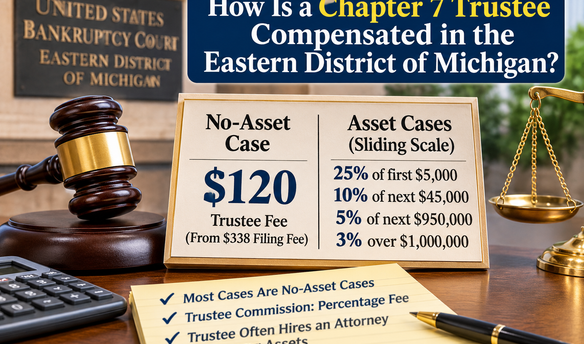
In most consumer Chapter 7 cases, the trustee ultimately determines that there are no nonexempt assets available for distribution to creditors. These are called no-asset cases.
If your case is a no-asset case, the trustee generally files a report indicating that there are no assets to distribute to creditors.
Once the required waiting periods have passed and all other requirements have been satisfied, the bankruptcy court will issue your discharge order.
For many of my clients, this is the beginning of their financial fresh start.
The Bottom Line: Don’t Be Afraid of Your 341 Hearing
I have represented more than 25,000 individuals in bankruptcy proceedings over the course of my career. I can tell you that the vast majority of Chapter 7 bankruptcy hearings are relatively routine.
The trustee is not there to judge you, criticize you, or make you feel bad about filing bankruptcy.
The trustee’s job is to verify your financial information, investigate your assets, and determine whether there is anything available to pay creditors.
The three areas that I would particularly emphasize are:
- Real estate: Make sure you disclose every property in which you have an ownership interest.
- Potential lawsuits: Disclose every potential personal injury claim or other legal claim, even if you have not hired an attorney.
- Bank accounts and inheritances: Be completely accurate about your account balances and any inheritance or life insurance proceeds you have received or may receive.
If you are honest, prepared, and have properly disclosed your financial information, there is generally very little reason to be concerned about the 341 hearing.
After more than 35 years of practicing bankruptcy law exclusively, I have learned that preparation makes all the difference.
If you are considering filing Chapter 7 bankruptcy in the Eastern District of Michigan, I would be happy to discuss your circumstances and explain exactly what to expect.
Walter Metzen
Board-Certified Specialist in Consumer Bankruptcy
Law Offices of Walter Metzen
313-962-4656
I have devoted my legal career exclusively to bankruptcy law, and I understand the procedures, trustees, and requirements involved in Chapter 7 bankruptcy cases throughout the Eastern District of Michigan.