Chapter 7 Bankruptcy Is an Exchange: Giving Up Non-Exempt Property in Exchange for a Fresh Start

Published
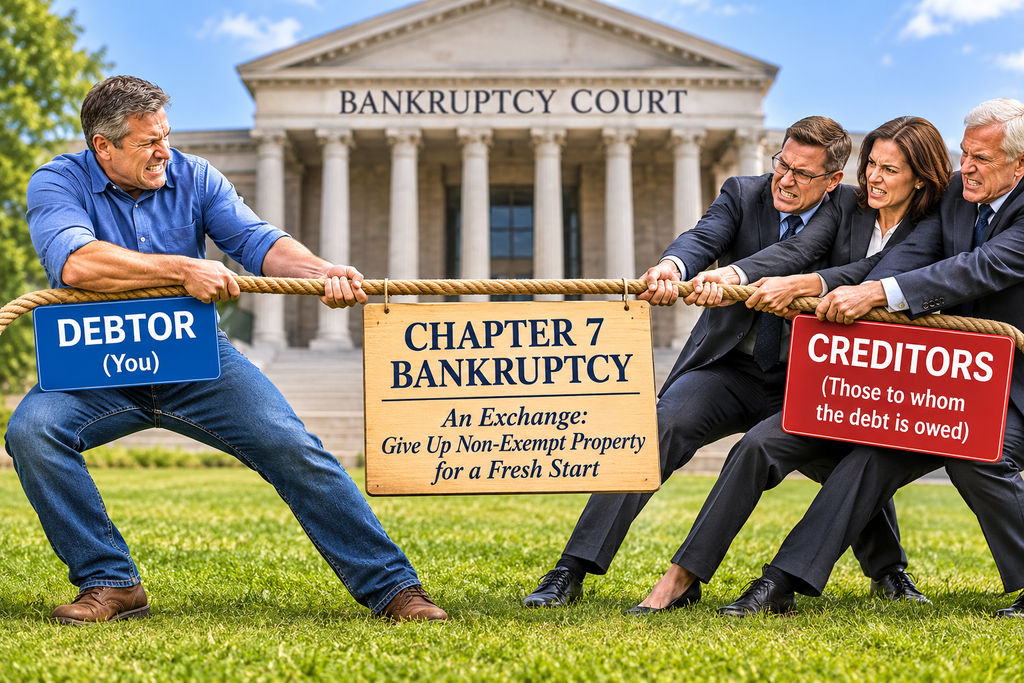
When I explain Chapter 7 bankruptcy to prospective clients, I often describe it as an exchange. The debtor agrees to surrender any property that is not protected by applicable bankruptcy exemptions. In return, the debtor receives something extremely valuable: a federal bankruptcy court order discharging (wiping out) most unsecured debts, including credit card balances, medical bills, personal loans, and other qualifying obligations.
It is important to understand that Chapter 7 bankruptcy is not simply a matter of filing paperwork and having your debts erased. There is a process involved, and there are two competing interests in every Chapter 7 case: the debtor who owes money and the creditors who are owed money.
I represent the debtor. My job is to protect my client’s interests, make sure all available exemptions are properly claimed, and help my client obtain a bankruptcy discharge while retaining as much property as the law allows.
The Chapter 7 bankruptcy trustee has a different responsibility. The trustee is appointed to administer the bankruptcy estate, identify any non-exempt assets, and, when appropriate, liquidate those assets and distribute the proceeds to creditors.
Let’s take a closer look at how this exchange works.
Table of Contents
The Debtor’s Side of the Exchange
When someone files Chapter 7 bankruptcy, virtually everything they own becomes part of what is called the bankruptcy estate. This includes bank accounts, vehicles, real estate, tax refunds, household furnishings, retirement accounts, and other property interests.
However, that does not mean the debtor loses everything.
The Bankruptcy Code and Michigan exemption laws allow debtors to protect certain property from creditors and the bankruptcy trustee. These protections are called exemptions.
Depending on the debtor’s circumstances, exemptions may protect:
- A certain amount of equity in a home.
- Equity in a vehicle.
- Household furniture, appliances, clothing, and personal belongings.
- Retirement accounts and certain other retirement benefits.
- Certain bank account funds.
- Tax refunds and other qualifying assets, subject to applicable exemption rules.
- Additional property under available wildcard exemptions.
The key is that exemptions must be properly identified and claimed in the bankruptcy petition. It is one of the reasons why having an experienced bankruptcy attorney is so important.
The debtor gets to keep exempt property. The trustee generally cannot take property that is properly protected by an available exemption.
In fact, upwards of 98% of the Chapter 7 cases I handle involve no assets available for distribution to creditors after exemptions are applied. In other words, the debtor is able to retain all of their property while receiving a discharge of qualifying unsecured debts.
This is why most Chapter 7 bankruptcy cases are referred to as no-asset cases.
The Trustee’s Side of the Exchange
The Chapter 7 bankruptcy trustee has a very different job from mine.
The trustee is not there to represent the debtor. The trustee’s responsibility is to administer the bankruptcy estate for the benefit of creditors.
After a bankruptcy petition is filed, a trustee is assigned to the case. The trustee reviews the bankruptcy petition, schedules, financial information, and supporting documents. The trustee also questions the debtor at the meeting of creditors, commonly called the 341 hearing.
The trustee is essentially looking for property or other assets that may be available to pay creditors.
For example, suppose a debtor owns a home worth $300,000 with a mortgage balance of $200,000. There is $100,000 in gross equity. If the debtor’s available homestead exemption does not protect all of that equity, the trustee may have an interest in selling the home, paying off the mortgage, paying the debtor the applicable exemption, and distributing the remaining proceeds to creditors.
The same analysis applies to vehicles, bank accounts, tax refunds, investment accounts, and other property.
The trustee also has the authority to investigate certain financial transactions, including transfers of property before bankruptcy, payments to certain insiders, and other transactions that may be recoverable for the benefit of the bankruptcy estate.
However, the trustee cannot simply take whatever property he or she wants. The Bankruptcy Code and applicable exemption laws establish what property is protected and what property may be administered.
If there are no non-exempt assets available for liquidation, the trustee generally files a report of no distribution, and the case proceeds toward discharge.
Chapter 7 Bankruptcy Is a Tug of War
I often think of Chapter 7 bankruptcy as a tug of war between the debtor and the creditors.
On one side is the debtor, who has become financially overwhelmed and is seeking relief from debts that can no longer reasonably be paid.
On the other side are the creditors, who want to recover as much of the money owed to them as possible.
The trustee serves an important role in this process. The trustee examines the debtor’s financial affairs and determines whether there are assets that can be recovered and distributed to creditors.
As the debtor’s attorney, I am on the debtor’s side of that equation.
My responsibility is to make sure the debtor receives every exemption and protection available under the law. That means carefully reviewing the debtor’s assets, identifying applicable exemptions, examining potential issues before filing, and responding to any objections or challenges raised by the trustee or creditors.
For example, if a debtor has $15,000 in a bank account, that does not automatically mean the trustee gets to take the money. We need to determine where the money came from, whether any portion is exempt, what exemptions are available, and whether the funds can be protected under Michigan or federal bankruptcy law.
The same is true when someone owns a home, has a vehicle with substantial equity, expects a tax refund, or has recently transferred property.
Proper bankruptcy planning can make an enormous difference in the outcome.
The Trustee Is Not the Debtor’s Attorney
One point I always emphasize is that the Chapter 7 trustee is not there to protect the debtor.
Although trustees are appointed by the United States Trustee Program and have duties under the Bankruptcy Code, their responsibility is to administer the bankruptcy estate and maximize distributions to creditors when non-exempt assets are available.
The trustee may question the debtor about financial transactions, request additional documents, object to claimed exemptions, or pursue the liquidation of non-exempt property.
There is nothing improper about this. It is part of the bankruptcy system.
But it is precisely why debtors should have their own attorney.
I have practiced consumer bankruptcy law for more than 35 years. I have appeared before the bankruptcy judges in the Eastern District of Michigan and worked with the Chapter 7 trustees in this district for decades. I understand what trustees look for, the types of issues that commonly arise, and how to properly protect a debtor’s interests.
My job is not to help the trustee find assets to distribute to creditors. My job is to protect my client within the boundaries of the Bankruptcy Code.
What Does the Debtor Receive in Exchange?
The most important part of the exchange is the bankruptcy discharge.
Once the debtor successfully completes the Chapter 7 process and satisfies the applicable requirements, the bankruptcy court enters a discharge order.
That order generally eliminates the debtor’s personal legal obligation to pay qualifying unsecured debts, including:
- Credit card debt.
- Medical and hospital bills.
- Personal loans.
- Certain collection accounts.
- Deficiency balances from repossessed vehicles.
- Certain older utility and other unsecured obligations.
The discharge is a powerful federal court order. It prohibits creditors from attempting to collect discharged debts from the debtor personally.
Of course, not every debt can be eliminated in Chapter 7. Certain obligations, including most student loans, domestic support obligations, and certain taxes, may survive bankruptcy. There are also exceptions for debts involving certain types of fraud and other conduct.
Secured debts require separate consideration. For example, discharging the personal obligation on a vehicle loan does not automatically eliminate the lender’s lien on the vehicle. If the debtor wants to keep the vehicle, additional considerations may apply.
Nevertheless, for someone overwhelmed with credit card bills, medical expenses, and other unsecured obligations, the Chapter 7 discharge can provide an extraordinary financial fresh start.
Is Chapter 7 Bankruptcy Worth the Exchange?
For most people considering Chapter 7 bankruptcy, the answer depends on what they own, what they owe, and whether their property can be protected through available exemptions.
If someone has $50,000 in credit card debt, $30,000 in medical bills, and little or no non-exempt property, Chapter 7 may be an excellent solution.
The debtor may walk away from tens of thousands of dollars in unsecured debt without losing any property.
That is the exchange.
The debtor receives a discharge of qualifying debts, and creditors receive whatever distribution, if any, is available from non-exempt assets.
In upwards of 98% of the Chapter 7 cases I handle, there are no assets available for distribution to creditors after exemptions are applied. The debtor keeps everything and receives the discharge.
But every case is different. Someone with substantial home equity, valuable investments, a large tax refund, or recent transfers of property needs to have those issues carefully evaluated before filing.
The biggest mistake someone can make is assuming that they will lose everything by filing bankruptcy. The opposite is often true.
Talk to an Experienced Michigan Bankruptcy Attorney
I have spent more than 35 years practicing bankruptcy law exclusively, representing more than 25,000 people who needed help dealing with overwhelming debt.
My practice is devoted to representing individuals and families in Chapter 7 and Chapter 13 bankruptcy cases in the Eastern District of Michigan.
If you are considering bankruptcy, the first thing we need to determine is what property you own, what exemptions are available, and whether Chapter 7 will allow you to obtain a discharge without sacrificing the property you want to keep.
Do not assume that you cannot file Chapter 7 because you own a home, have a vehicle, have money in the bank, or receive a tax refund. Those assets may be protected.
Call my office at 313-962-4656 to discuss your situation. I will explain how the Chapter 7 process works, what property you can protect, and whether bankruptcy is the right solution for you.
The goal is simple: protect what the law allows you to keep and eliminate as much qualifying debt as possible so you can move forward with a fresh financial start.